Tuesday, January 24, 2017

Additional Insured's - Professional Liabliity Part 2


WAIT......WHAT?
In my prior related post (published Nov 10, 2016) I discussed the concept of an Additional Insured (AI) and the professional liability policy. For years carriers writing E&O coverage have either not been willing to add AI's, or have done so with limitations. The market has evolved as it always does and competitive pressure along with a few other factors have caused many carriers to loosen up those guidelines. Getting an AI added to a professional liability policy is indeed easier on many classes than it used to be, but don't take that to mean AI status is always going to be available. And even if the carrier agrees to do so, you still have some things to consider, which I'll outline. First understand that companies that write E&O and Professional Liability don't all treat this situation the same, and they fall into four main categories (according to me) regarding AI requests:
  1. They can't because it's a "treaty" exclusion, i.e. whoever is providing their reinsurance has said this is not an option. That one doesn't come up very often in our current marketplace.
  2. They won't because they argue there's little or no coverage for most AI's on an E&O policy. I'll explain that in a minute.
  3. They will add an additional insured, but they'll charge for it, frequently more than the customary $100 or so, and typically will not give much leeway when it comes to language regarding other entities, i.e. affiliates, ATIMA, etc. They may or may not offer waiver of subrogation and/or primary non contributory wording. Usually they won't offer a blanket AI option either.
  4. They'll offer AI wording, and will accommodate those requests with the same or close to the same level as a GL carrier. Due to market pressures and the need to do something more than the competitor, this option is becomeing available more and more.
To make your life a little easier when you run into these situations, here's some information that may help you work things out with the underwriter, or at least be able to properly explain the circumstances to your customer.

Insured vs Insured exclusion. The theory is if you add an AI to a policy you now make them an insured, and if the policy has an insured vs insured exclusion, they will be prevented from bringing action against "themselves". Jurisdiction, prior legal precedent, how big the claim is and who has the best attorney all factor into this pot of goo. Just understand that it's a consideration and you need to know if it applies on the policy you're working with.

How about the claims trigger, you ask. GL policy claims are typically triggered by third party damage, such as BI and PD. Tangible stuff for the most part. Professional liability claims are triggered by an act, error or omission in providing or failing to provide professional services. If you add an AI that offers no professional services to a policy intended to provide coverage for an entity that does provide professional services, does the action of the AI trigger policy coverage? And what about adding an AI that would be covered by a different type of E&O policy - does that prevent the policy from responding? It's not an issue if all you're after is defense coverage for the AI in the event the insured commits E&O, but make sure the endorsement wording doesn't create new problems.

Reducing policy limits, maybe.  Make sure your client understands that the greater number of entities "sharing" the policy limits means that in the event of a covered claim with an AI, or more than one, everyone is pulling from the same stack of cash. Everyone has to eat, so I do understand that sub-contractors and smaller entities may take on contracts without regard to the requirements just to get the work, but at the very least they should be made aware of the possible downside.

YOUR E&O could be at risk. Brokers do a great job of getting things accomplished for their customers, whether there is enough time to reasonably expect anyone to do so and whether or not the client has any idea how much work may be involved. But be careful. In the prior paragraph I gave an example of where this can come back and bite you in the, uh, assets. If you don't explain to your client that their limits can be eroded or eliminated by adding one or more AI's, you can bet their new BFF attorney will spell it out for them. Same with other possible problems that occur in these situations.

When you're adding an AI make sure you review the policy to see if you're creating a new problem. Ask the underwriter and if they're not sure ask the underwriting manager. Just make sure you can explain it to your customer. Remember you're supposed to be working on THEIR E&O, not YOURS!

Tuesday, November 29, 2016

OVERTIME
Curtis Samuel scores the winning touchdown in the second overtime for Ohio State. (Greg Bartram/USA Today Sports)
Overtime can be a major problem for you if you're a sports fan rooting for the team on the short end of the game score. That's one type of overtime. Overtime can also be a major problem for you or your client if they're facing a "claim" for back pay from a disgruntled employee. Or "better" yet, suit papers from a not so friendly law firm.

Before I could add the second part to the additional insured post from a couple weeks ago, some interesting things happened in the world of Employment Practices Liability (EPL). That triggered this post, as the rule itself is not as important as the overall subject matter.

New overtime rules for "while collar" workers, part of the Fair Labor Standards Act (FLSA), were to take effect as of December 1, 2016. The new OT rules, if or when they go into effect, change the "exempt" employee qualifying amount of compensation (one of several "tests" to determine eligibility) from $23,660 per year to $47,476, which is basically double. That means business owners that are not paying attention will immediately be out of compliance for any "exempt" employee making less than $47,476. 
As respects this rule, a Texas judge has issued a preliminary injunction. That injunction stems from a legal case brought by several states and business organizations. The injunction is not permanent, so the "freeze" on implementation by the Department of Labor may or may not be for long. Opinions differ as to whether the new rules will ever be implemented, and as you can imagine the reasons are mostly political in nature. But either way I'm guessing you're wondering what this has to do with you.
The problem. Odds are that some of your customers are in trouble and just don't know it, either due to their business practices related to non-exempt employees, or the fact that they don't have EPL including wage and hour coverage, or both.
Several years ago plaintiff attorneys discovered that the employment practices of many businesses are ripe for legal action. This occurs in at least two areas related to wage and hour, 1) mis-classification of exempt employees and 2) poor or no record keeping regarding overtime hours for non-exempt employees. Some business operations do a fair to poor job of properly identifying who is and who is not an "hourly" employee, and that mistake compounds over time.

One common misconception is that classifying employees is up to the employer. It's not as there are Federal guidelines and "tests" to be applied that don't leave much room for subjectivity. Even if the employer gets the classification correct, those employers that don't keep accurate records of hours worked open themselves up to suits alleging that back pay is owed for OT - almost always from former employees. The onus of responsibility in these situations is on the employer to prove they have accurate records of both hours worked and the payment for those hours.

What to do? First, your customers need to know the rules that exist now relative to exempt and non-exempt employees and how to properly apply those rules in their business operations. If they don't know for certain they need to ask for help to be sure they're following the rules that are established. That may or may not require a consultant, but given the cost of a consultant vs fines, penalties and legal costs, it seems like a pretty easy choice. Second, review their current EPL policy to see if that policy provides defense for wage and hour law violations (part of FLSA). If the policy does provide wage and hour language, read it. Most policies are defense only, i.e. no indemnity coverage, and most only offer a sub-limit, usually $100K.
If they don't have EPL coverage in place, quote and bind coverage for them asap and make sure you explain what is and is not provided by that policy.

I'm fairly certain that if you do a little reading and get current on this issue, you'll be a huge resource to your customer and separate yourself from many of your competitors on this subject. If you have questions or want to discuss the topic, let us know and we'll be happy to help.

Thursday, November 10, 2016

Choices and Options and Bears. Oh My.

 
It seems that many of the fun things I do these days have something to do with my grandson. Earlier this year when the weather was warmer we made a trip to the Cleveland Zoo. Cleveland has a great zoo in my humble and totally unscientific opinion.  And there are MANY choices and options as to where you can spend your time and energy. We navigated through the day reasonably well, but I have to admit once we saw the lions and tigers and bears, we spent the rest of the day making it up as we went. We had fun and it was a successful trip, but it could have been much more efficient and a little less stressful if we were a bit better informed.

In our current insurance marketplace, being informed and having a plan is critically important given all of the options we face every day. What can make it more challenging are the various positions insurance carriers take on a variety of issues. I’ll use a fairly common subject as an example; adding entities as additional insured to an Errors and Omissions (E&O) policy. (this could also apply to D&O and/or EPL)

When writing a GL policy you know that just about everyone hiring sub-contractors requires that the sub name the hiring entity as an additional insured (AI). In addition it's not uncommon to see requests for waiver of subrogation and primary non contributory wording to be added as well. And then there's the job or entity specific AI wording, usually requesting everybody and their brother/sister to be included in the AI wording.

In the world of E&O insurance, it's not that easy. In the past few years, more carriers have been willing to consider including entities as additional insured on an E&O risk, but there are still many carriers and classes where it's limited or not an option. Why would a carrier balk at doing this, and just as important to you, how can you advise your client on this subject? I'll list some reasons for you to consider, and in the next post I'll explain why this is an issue, as well as some discussion points you should consider with your customer.

1.  There may be an "insured vs insured" exclusion on your client's policy

2.  The incident in question may not trigger the policy coverage provisions. Professional liability and/or E&O policies are triggered by an error or omission in providing or failing to provide professional services.

3.  The insurance carrier in question has a reinsurance agreement and the reinsurer will not allow or accept AI's on the policy.

4.  Your customer may suffer a reduction in policy limits in more than one scenario

5.  You  may be open to an E&O claim by adding an AI

If you have a situation that's pressing and can't wait until the next post, by all means call or email and I’ll be happy to help. Call 800-442-8063 xt 171 or email at thoelle@tuscano.com


Tuesday, June 18, 2013

Beginnings and Endings, or Not.

Sculpture on the grounds at Columbia University, NYC
I'm not a huge fan of contemporary art, and by comparison my step son is quite the scholar and critic, so I'm trying to be open and learn. As respects the piece in the photo above, I'm drawn in by the geometry and it's complexity. I must admit that I have no idea if there's a beginning and an end, and more than likely if I'd ask the artist they'd ask what I think, or what do I see or something similar. Sigh.

Not being able to clearly identify the beginning and the end is fine in the world of art and I'm sure in many other "places", but it really makes life complicated when professional services are being rendered or offered. Most professionals - and their clients - can tell you with some certainty when a professional relationship began, but all too often there's nothing quite so clear when it comes to the end of the relationship.

Law firms, and some other professionals, use engagement letters when signing up a new client, and they use (or they should use) dis-engagement letters when firing a client, or when the client takes their business elsewhere. Not doing so is simply an open door for misunderstandings, and unfortunately these days that could spell trouble. And trouble in this case is spelled l-a-w-s-u-i-t.

If your clients are providing professional services and not using written contracts they're asking for problems. It may not seem like it has anything to do with their questions about insurance, but if your client is still doing business in a very informal way, especially if they have some assets at risk (and they do), it would be wise to encourage them to be a bit more proactive. And by advising your clients accordingly you will be helping your own agency avoid potential errors and omissions issues.

There's a very good post about this by a law firm called Goldberg Segalla with some case study info provided. Here's the link http://professionalliabilitymatters.com/2013/06/05/the-break-up-knowing-when-the-professional-relationship-is-over/

It would be nice to think that the world still functions as it did "back in the day", but as we know things have changed and not always for the better. If you need some help finding resources, making suggestions to your clients, etc just let me know. I'd love to give you some tools to work with.


Thursday, May 30, 2013

Architects and Engineers - This Could Be Big...

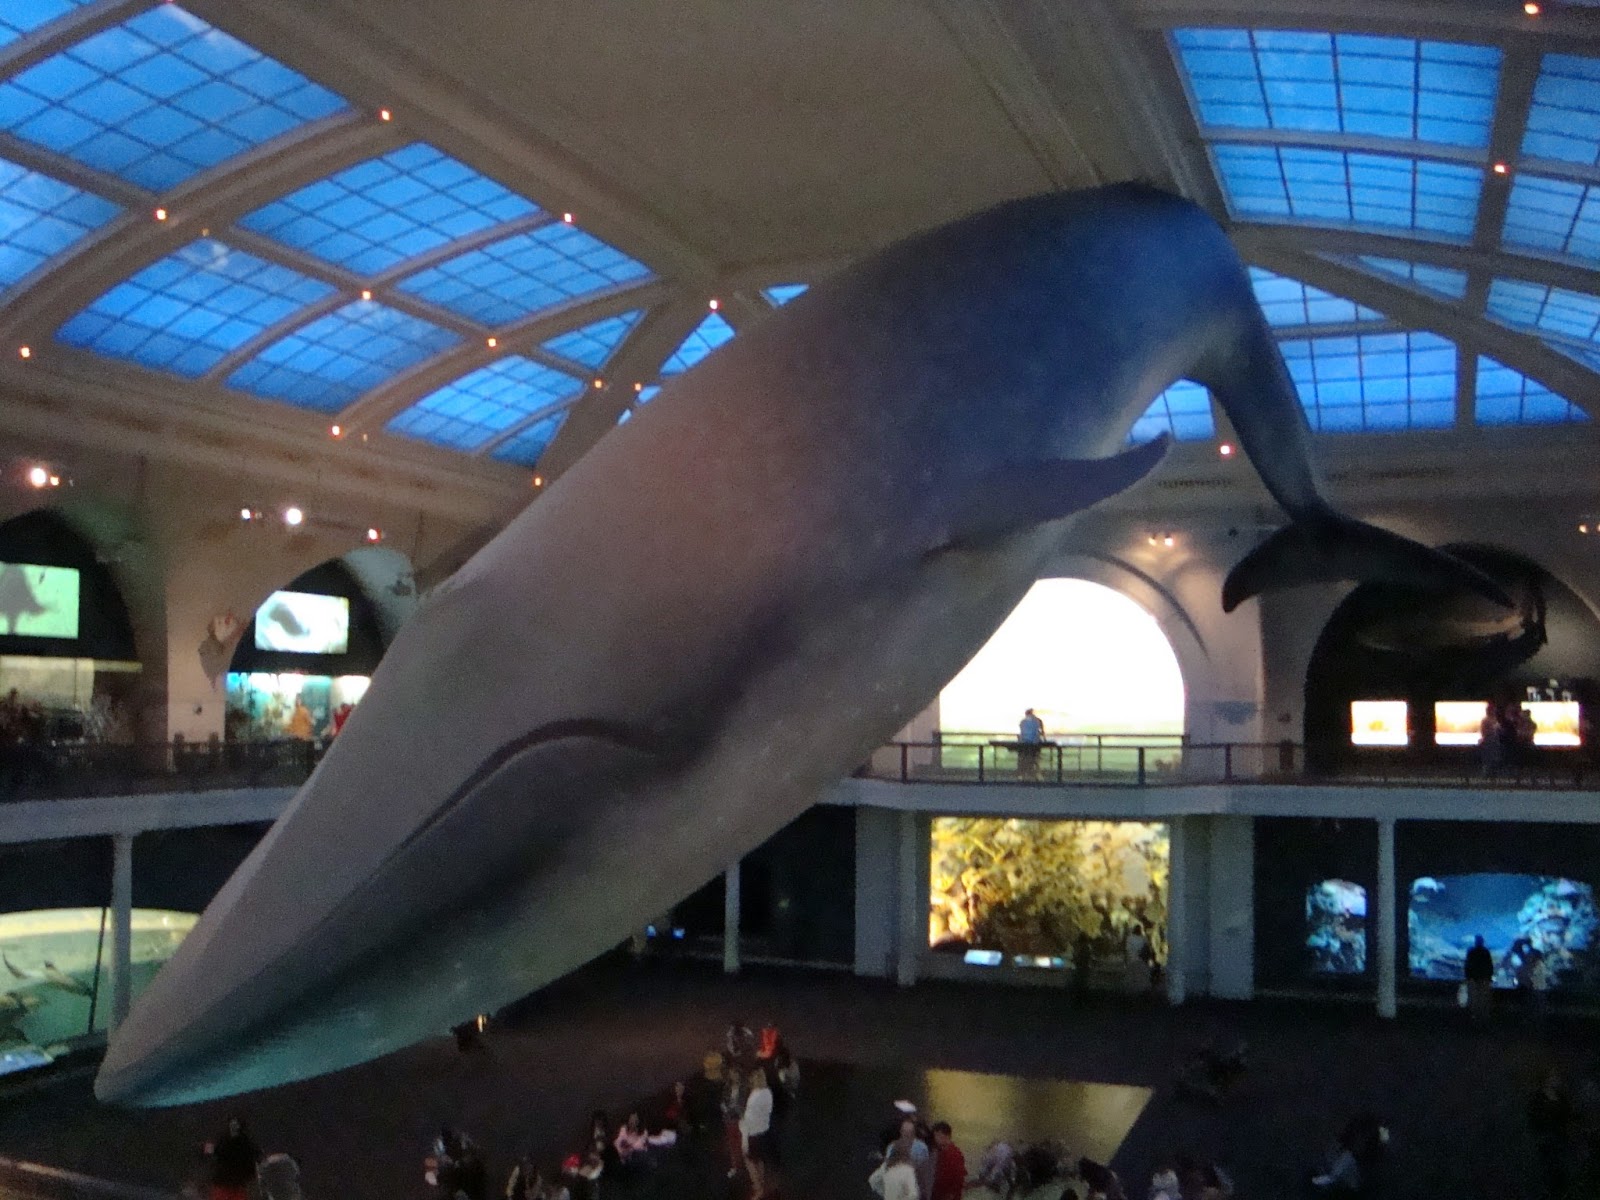
Whales: Giants of the Deep    Natural History Museum, NYC
On a recent trip to NYC six of us kids (OK, five "adult" kids) and our two year old grandson made a stop at the Natural History Museum. We wanted to see one of the newest exhibits, and the photo above doesn't really do justice to either one of two engineering feats - the whale itself or the exhibit created by the museum staff. This is an impressive display, and I can only imagine the difficulties encountered and problems faced by those creating the exhibit.

I'm constantly amazed at the ability of architects and engineers to successfully solve problems, especially unique or complex ones. Successfully solving problems is part of our jobs as insurance professionals and certainly part of your daily routine as an agent. Our goal is to equip you to be able to handle those challenges, and we have another tool to help you do just that.

One of our carriers successfully writing Architects and Engineers professional for decades has released a new policy form. This new version includes many coverage features that are beneficial to your customer. Some of these features appear on other forms, but few if any other carriers provide all of these on one form. We're pleased to be able to offer it to you.

Here are some of the high points:

Deductible Credits:  This form offers numerous deductible credits, and most carriers today only offer mediation deductible credits. Per American Council of Engineering bench marking - 45% of claims are settled by negotiation, 31% mediation, 7% arbitration, 3% trial and 6% other. This form provides incentives and the tools for handling claim situations quickly, and of course that's better for all parties involved. Chances are good your client may not even pay the deductible on this policy form. Credits as follows:
·        3X's Aggregate Deductible (competitors are "each and every")
·        LEED certified buildings (50% up to $25k)
·        Award-winning buildings (50% up to $25k)
·        Claims resolved through mediation (50% up to $25k)
·        Claims resolved through negotiation (75% up to $25k)

Supplementary payments: This form offers some of the broadest supplementary payments available in the market.
·        Loss of Earnings - $500 per day/up to $15,000
·        Regulatory and Administrative Actions coverage - up to $25,000
·        Subpoena/Record Request - up to $5,000
·        Professional License and Disciplinary Proceedings coverage - up to $50,000

Some additional features/benefits:
·        Claims Made (not Claims Made & Reported)
·        Pre-claims assistance 
·        Risk management services
·        Contract review services


Send new business to submissions@tuscano.com or call 800-442-8063 to obtain apps or additional information.

Monday, May 13, 2013

Professional/E&O Market Challenges

Oglebay Golf Resort, Palmer Course, Wheeling WV

I recently had a chance to play some golf in West Virginia. I'm used to playing on fairly flat ground, and about half of my shots in WV were not on flat ground. As you can see from the photo above, in the background on hole number one there's a ski lift - a good clue that the terrain isn't going to be "easy". It was quite the challenge, to say the least.

Whether it's personal relationships, sports, business or something else, one thing for sure is that over time we will encounter challenges. In the business of insurance, these days a "challenge" is the norm and not the exception. As our company underwriters adjust their appetites based on claim experience, financials or home office directives, we work hard to keep up with what is happening with our markets. Here's a snapshot of some of the things we're seeing:

Architects and Engineers: The companies writing these classes are still very aggressive on pricing for entities with routine operations. Markets are still competing for business, so on the majority of risks there's plenty of options, regarding both pricing and terms. Difficult placements include:
  • structural or geotechnical engineers
  • firms that do more than a small percentage of design/build
  • operations involving oil and gas
  • engineering firms that design and manufacture a product or products
  • work involving condominiums
  • very small revenues combined with any of the characteristics listed above 
Miscellaneous Professional:  The majority of risks that fall into this category are consultants of every flavor, but as you probably know almost any business operation that provides professional services can fall into this category. Most markets like just about every consultant risk that you can present, but here are a few classes that are tougher to write, consulting or otherwise:
  • credit repair and/or debt settlement services
  • real estate services. That would include title agencies, law firms specializing in real estate practice and mortgage brokers. Also real estate agents that generate a significant portion of their revenue from short sales and foreclosures is still a challenge for many of the admitted markets. And real estate agents or property managers selling or managing a large percentage of their own properties is another difficult risk for most insurers.
  • armed security professionals
  • financial advisers/financial consultants 
Accountants/CPA/Bookkeepers: This class is extremely competitive for risks that have very routine services. Bookkeepers premiums can be as low as $300. The harder to place accounts typically have one or more of these characteristics:
  • heavy audit work, especially public company audit
  • SEC related work
  • business forecasting/projecting
  • business valuations
  • financial or investment advisory
  • mergers and acquisitions
  • management advisory services
  • custom software sales/training 
Other issues may make a risk hard to place, including prior claims or incidents, new in business and/or disciplinary proceedings or actions against a licensed professional.  We have the markets and experience to help you work though the scenarios listed here as well as almost any other situation you encounter. For information on other classes or to discuss a risk, call 800-442-8063 or email tim@tuscano.com today.

Tuesday, December 11, 2012

Data Breach Part IV - Coverages

Photograph by Ofer Wolberger, Popular Mechanics July 2010
Most of us know that the lock on the door of our house is sufficient to prevent someone from gaining easy access to our property. It's been said that locks keep honest people out. But we also know that if someone is really determined they can breach the majority of security measures we might have in place. If they're really skilled, they can do so rather quickly. The same is true with our computers and the date stored on them, especially those used in a business operation. 

As business and government operations rely more heavily on computers to perform tasks and store data, more criminals, hackers and terrorists are turning toward computer related crimes to either make money, cause damage or both.  In the past few years there's been a significant spike in cyber crime and there's no reason to believe the rate of incidents will diminish anytime soon. The FBI's Internet Crime Complaint Center (IC3) states they received over 314,000 complaints of online criminal activity in 2011 (2011 Internet Crime Report). That's the third year in a row incidents topped 300,000, and that's just what was reported to them.

Insurance carriers are trying to keep up with the changing landscape by crafting new coverage options and improving existing wordings and features. Here are a few of the current options that may be available to your client (terminology may vary slightly from carrier to carrier, and some coverages provided, especially first party, will usually be subject to a sub-limit):
  • Network and Information Security
    • claims arising from the unauthorized access to data and that's usually personally identifiable information
    • failure to provide notification of a breach (as required by law)
    • transmission of a computer virus or similar
    • liability associated with the failure to provide authorized users with access to the company's website
  • Communications and Media Liability
    • coverage for claims arising from copyright infringement, plagiarism, libel, slander in electronic content
  • Defense Expense
    • coverage for governmental claims as a result of network and information security liability, and/or communications and media liability
  • Security Breach Remediation and Notification Expense (first party)
    • costs incurred to determine whose identity information was accessed
    • cost of notification to customers/others of the security breach
    • identity fraud expense reimbursement for those individuals affected by the breach
    • credit monitoring services for those notified (usually for 12 months)
    • call center services to assist with inquiries
  • Computer Program and Electronic Data Restoration Expenses (first party)
    • expenses incurred to restore data lost from damage to computer systems due to computer virus and/or unauthorized access.
  • Computer Fraud (first party)
    • coverage for loss of money, securities or other property due to unauthorized access to computer systems
  • Funds Transfer Fraud (first party)
    • coverage for loss of money or securities due to fraudulent transfer instructions to a financial institution
  • E-Commerce Extortion (first party)
    • money paid due to threats made regarding an intent to destroy data, introduce a virus or attack a computer system, disclose customer info or other similar threats
  • Business Interruption and Additional Expenses (first party)
    • loss of income and extra expense incurred to restore operations, must be a result of a computer system disruption caused by a virus or other unauthorized computer attack
This is a fairly representative list, but each carrier tries to offer something a little different, so exact terms will depend on the unique qualities of the  business, and the carrier offering coverage(s).  Also, it's not necessary to buy all of the coverage options, usually the coverages can be purchased in sections or modules. Contact us today for a quote or help determining how to best address your client's needs.

Monday, November 5, 2012

New Product: GL and E&O For Consultants

We have a NEW product available providing E&O and GL for entrepreneurs and small businesses providing consulting services. Competitive quotes are available quickly.

Coverage includes:

  • Defense outside the limit (capped at the aggregate policy limit)
  • HIPAA/HITECH sublimit of $250,000
  • Automatic additional insured coverage
  • Contingent BI/PD sublimit of $250,000
  • 50/50 cooperation clause
  • Third party discrimination coverage
  • Independent contractor coverage

Risks are not eligible for this product if they've generated more than $1 MILL in revenue during the past 12 months and/or if they've had an E&O claim in the past five years.

Also, your client's services must be in an acceptable category. Some of the services not acceptable for this program include: intellectual property, copyright or patent work, employee benefits or pensions, medical related work,  services associated with an architect, engineer, attorney or real estate.

If your client does not qualify for this product due to claims, services offered and/or revenue, we have multiple markets available to allow us to quote them as well.

Call or email today for a quote.

Tuesday, October 16, 2012

Tuscano’s Hand Improves (New Market Added)

aces
I just received confirmation that our appointment with ACE Commercial Risk Services has been finalized and is effective immediately. I’ve had several conversations with customers over the past few months that convinced me this would be a good and necessary move for us.
Premiums and coverage forms are very competitive, and classes of business include the following:
  • D&O (For Profit and Not For Profit)
  • Technology E&O, and Data Breach, Privacy and Network Security can be included or written stand alone
  • Environmental Contractors
  • Stand Alone Contractors Pollution
  • Miscellaneous E&O (incl TPA’s, Trustees, Real Estate agents, Temporary Staffing, Construction Managers, Property Managers and more)
ACE is another great card in the deck that we can offer to you, our customer. Combined with an already strong group of markets and the service and professionalism you’ve come to expect from Tuscano, you’ll be playing to win.
If you’ve been stuck gambling on another broker to get this done for you, or if you’ve never worked with ACE, now’s the time to ante up and contact us. We’re betting you’ll be happy you did!

Wednesday, October 10, 2012

Criminal Justice Service Operations Insurance

doc_central_office___tech_park
Department of Corrections Corporate Offices, Mechanicsburg PA
Here’s a quick reminder that we have the ability to write general liability, professional liability and property coverage for a variety of operations within the criminal justice system.
The professional and GL are on the same policy; the property can be written by the same carrier but the policy would be separate.

Our carrier is rated A+ (Superior) by A.M. Best Company.

Summary of Coverages:

General Liability, Professional Liability

- Sexual misconduct

- Civil rights coverage

- Hired & non-owned auto coverage 

Optional Professional Liability Coverage

- Employment practices liability

- Stop-gap coverage

- Law enforcement coverage

- Medical malpractice for prison nurses

- Medical malpractice for prison physicians

Property Coverage

- ACV-replacement cost-agreed amount

- Minimum premium: $1,500

- Minimum deductible: $1,000

- Special rating considerations in program

- Building, contents, equipment, business income, extra expense and crime exposures

- Equipment floaters available
Available for:

  • Adult and juvenile boot camps
  • Court-ordered counseling
  • Community correction centers
  • Drug and alcohol treatment centers
  • Electronic monitoring companies
  • Halfway houses
  • Law enforcement trainers
  • Offender rehabilitation classes

  • Other staff secure juvenile facilities
  • Pre-release centers
  • Prisoner transportation companies
  • Probation services
  • Public and private prisons and jails
  • Restitution centers
  • Work release centers

Call or email us today for more information…

Thursday, September 27, 2012

Data Breach Part III - What It Is

dam breachNot being able to visually depict a data breach, I found a photo of an earthen dam being breached. Similar to water, when data is not contained where it’s supposed to be, the result can be damaging and costly.
Data Breach coverage is first party coverage, meaning it’s intended to provide coverage to your client if they experience a loss of THEIR customer’s *personal information. There’s no need for the policy to be triggered by a suit or other demand for damages as you would expect in a third party claim. ( *personal information includes credit card numbers, driver’s license numbers and/or social security numbers. Most of the U.S. Government’s info on this subject refers to such customer info as “personally identifiable information”, or PII; some carriers are simply calling it “personal information”, or PI).
In addition, even if they don’t have thousands of customer records containing PI that is lost or stolen, the fact that this info COULD have been compromised is usually all that’s necessary to trigger notification requirements spelled out in state and federal laws. Simply put, your client could very well be on the hook to send out written notification to ALL of it’s clients, even if only one record is lost or stolen.
In addition to existing federal laws, forty six states have enacted laws regarding notification. The notification requirements are not standardized, and if your client has customers in multiple states the likelihood of your client knowing the statutes and being able to quickly and easily comply with them is slim and none, and you guessed it - slim has already left town. The cost of a reputable, qualified third party to perform the notification task for your client varies greatly based on territory and some other factors, but I’ve seen estimates from $50 to $250 per customer record.  (if you need help explaining the reason for the costs being so high, I can help with that)
If you want documentation of those costs, there aren’t a lot of options available just yet, but try the report from Ponemon Institute in association with Symantec. For the events they could verify, they show that the cost of notification for 2011 was $194 per record. http://www.symantec.com/about/news/release/article.jsp?prid=20120320_02
This report also shows the difference in breach event costs between companies that have chief information security officers and those that don’t, as well as several other factors.
Other “hard” costs that your client may have to deal with are regulatory costs and credit monitoring services. Regulatory costs could include fines, penalties and/or the establishment of a compensatory fund – all as determined by the regulator. Your client must also provide credit monitoring services for those customers who may have had their information compromised. It’s usually a requirement for a company that’s had a breach to provide their customers with at least one year of credit monitoring services from a qualified third party vendor.
In addition to hard costs there are “soft” costs that are likely to be associated with a data breach; abnormal turnover of customers, increased customer acquisition (or re-acquisition) activities, reputation losses, as well as diminished goodwill.
Obviously there’s more to consider, but hopefully this gives you an idea of what’s at stake and helps you evaluate which of your customers may need to consider this coverage. In the next post I’ll look at coverage options available.

Tuesday, September 11, 2012

Remembering, Honoring

am flag half mast

An American flag flies at half staff next to a twin towers statue at Tyrrell Park in Beaumont in 2011. Guiseppe Barranco/The Enterprise

I feel compelled to post something today regarding the anniversary of 9-11. I know it’s not going to be profound or life altering, but it’s important to me to do so.

On September 11, 2001 in New York city many innocent lives were taken and many others were injured. And for those of us who were somewhere else at the time, we were impacted in some way. I hope people take a moment today to remember those who died and those who were permanently damaged physically and/or emotionally. And to remember those who tried their best to help their fellow human beings, many of them at the loss of their own lives.

I think that’s what I want to remember as much as anything else, that people still care about other people. That we can actually do something good and positive for others around us, even if we don’t know them at all.

We can’t change what happened, and I for one still can’t really make sense of it. But I know that I can do something to remember and honor those human beings that died that day. I can find someone today that I can help, or encourage or love. Maybe more than one someone, and maybe not just for today.

Monday, August 27, 2012

Data Breach: What It’s Not

universal no symbol

To discuss data breach coverage I think it’s important to understand what it is not, as well as what it is. As stated in the previous post, as far as I’m concerned data breach is not cyber liability. Insurance companies may market a product as “cyber”, but “cyber” means anything computer related. Just adding “cyber” to the word “liability” doesn’t really mean anything specific, and it certainly isn’t a clear indication that the coverage is/includes data breach. Instead of me re-stating all of my comments, check out the prior post by clicking on this link:  http://tuscanopro.blogspot.com/2012/08/most-misunderstood-insurance-terms.html

Data breach is not third party coverage; i.e. it’s not intended to defend your client or provide indemnification on their behalf for an error or omission generated by their work product. Third party liability assumes that another entity is asking for or demanding monetary damages because of an act, error or omission by your client. While a data breach will probably result in costs to your client, some if not all of those costs are not going to be covered by an E&O policy form that does not include a data breach coverage part.

Data breach is not a package policy that includes GL, Non-Owned and Hired Auto, Crime, etc. I don’t think there’s anything wrong with a “package” that includes E&O, it’s just not necessary to write a package to provide data breach coverage.

I think the most common misunderstanding I’ve encountered so far  is being asked to provide data breach coverage for technology service providers not storing critical customer data, including website designers, consultants, hardware and software resellers and programmers. While each situation is unique, If your client isn’t storing/keeping this information, their data breach exposure is probably minimal. (The next post will better define “critical customer data”, but if you want to do some research on your own and get ahead of the curve, do a search for “personally identifiable information”).

If you’re looking for a couple of diagnostic questions to determine if your client has a data breach exposure, you should probably start with questions regarding how many customer records they store, usually electronically, and what type of information is in those records. If your client/prospect does store credit card numbers, medical records, driver’s licenses numbers and/or other similar information, they have a data breach exposure.

The next post will look at what data breach IS…

Monday, August 13, 2012

The Most Confusing Insurance Term Is…

borgThe concept of Cyber Liability is confusing enough - don’t complicate things by confusing Cyber Liability with Cyborg Liability. At this time, I don’t have any markets available for the latter. But you never know…

(First in a series)

I’m sure there are many insurance terms that aren’t clearly understood, or that don’t really describe what the coverage is, but my vote is for “Cyber Liability”. Let’s face it, we are now reading and hearing about “cyber” everything. Cyber bullying has become a major issue, especially for school age children. I’ve seen a number of commercials for cyber knife medical technology. And of course there are many others, including cyber space, cyber crime and cyber security.

Merriam Webster online dictionary defines cyber as: “of, relating to, or involving computers or computer networks (including the Internet) <the cyber marketplace>”

Based on that definition, then cyber liability could be insurance for your client whenever they’re using the internet. Or perhaps it’s any insurance coverage involving computers or computer networks?   I think I’ve seen requests for cyber liability that involve all of these areas of exposure/operations and more.

Here’s what I think most people mean when the term “cyber liability” surfaces - more than likely they’re referring to an insurance product that’s meant to provide some level of coverage for a data breach, also called an information security breach.

The simplest way I can define or describe a data breach is when  personal information – usually critical financial info – of your insured customer is lost or stolen. In fact, the data really doesn’t even have to be lost or stolen. If your client retains credit card, drivers license and/or other personal financial info, and their network is hacked, they lose a laptop or other electronic device and the info may be at risk, your insured has an obligation to notify their clients. That can be costly, so you need to make sure the policy either covers those costs, or you advise your client that is does not.

In subsequent posts, I’ll get into coverage details, applicability to some of the business operations you may encounter and so forth. In the meantime, if you have questions or need some help sorting out a current quote – call Tuscano. And yes, resistance is futile.

Monday, July 16, 2012

New Professional Liability Opportunities in PA

paralympics race

If you get a chance to watch the Paralympic Games I highly recommend it. I’m guessing you’ll be amazed and inspired  by what competitive desire, hard work and technology can do.

Pennsylvania House Bill 48 of Session 2011, amended June 27, 2012, may provide you with an opportunity to write new business for some of your existing customers. And if you’re not aware of any existing accounts that fit this profile, it may give you reason to knock on some doors of local business owners.

The bill requires, among other things, that orthotists, orthotic fitters, pedorthists and prosthetists purchase and maintain professional liability in the amount of $1 MILL per occurrence or per claim.

All of these professions are related to the evaluation, design, fabrication, assembly, fitting and/or adjusting of artificial limbs, or braces or appliances to support poorly functioning or non-functioning limbs or joints. If you want to see a more detailed definition for these professions as listed in Bill 48, here’s the link:  http://legiscan.com/gaits/text/657475

Bill 48 is directed toward licensed professionals and requires the work being done to be as a result of a written prescription by a physician, physician assistant, nurse practitioner, etc.

If you have questions regarding these professions, if you need an application or want to discuss current policy coverage, let me know.

Monday, July 2, 2012

Mgmt Liability/EPL/D&O Market Update–Part 2

bar
Bars, Restaurants, Hotels and other “Hospitality” industry risks are high on the target list of plaintiff firms re wage and hour lawsuits.

The prior post outlined likely market changes for D&O in the next 12 months or so, this one will focus on Employment Practices Liability.

Rates are up, but only slightly. Many carriers would love to see a 15% to 25% rate increase, but expect rates to increase 5% to 10% for loss free accounts. Rates will definitely increase more on risks with claims, as will retentions, and how much depends on the details of the loss(es), type of entity and the state (possibly even the county)  where the risk is located. The real change is going to be on the underwriting side, as carriers will start - if they haven’t already started - to tighten up the filter on new and renewal business.

The reason for that is claim frequency and severity has increased for just about every company I’ve spoken with, and we’re going to blame the economy again, at least in part. Employers that are struggling financially are trying to get more work out of fewer people, which can translate to longer hours and higher stress levels for employees. It’s also possible many hourly employees are working more and not being properly compensated, and unfortunately sometimes the employer doesn’t realize they’re not in compliance with state or federal law (until their former employee’s attorney contacts them)

Another driver is some employment law has become a little more  employee “friendly”. An example of this is the ADA Amendments Act of 2008. The Act went into effect January 1, 2009, with the EEOC regulations to implement the equal employment provisions of the Act effective as of March 25, 2011. One of the results of the Act is that it expanded the definition of “disability”. How much impact these changes have had is hard to measure at this point in time, but a couple of the underwriters I spoke with indicate they believe there is some impact regarding new claims.

And one other very specific reason frequency and severity is up is that the plaintiff bar is still very active regarding wage and hour claims. In my part of the world if I do a web search for “overtime laws” or “overtime claim” the first two websites that come up are local plaintiff firms. And they are on billboards, tv and radio, as you probably know. If you have customers with a decent number of hourly employees and you have not offered them terms that include wage and hour defense coverage, I would strongly urge you not to offer another renewal without that option included. If for some reason it’s not available to your client, at least you’ve done the work needed to confirm that and advise your customer accordingly.

We are still seeing companies enter the market re EPL, but compared to 3-5 years ago the numbers are down. And carriers are way less inclined to add more coverage - probably the most recent coverage enhancement or option is illegal alien investigation coverage.

The market is still very competitive, no doubt, but it appears we may have reached the “floor” when it comes to rates. And we may actually see more underwriting in the next 12 months or so.

Monday, June 25, 2012

Management Liability/EPL/D&O Market Update

ducksManaging effectively – without having your ducks in a row? 

From China Daily/Reuters via MSN: A farmer snarls traffic in China herding 5000 ducks to a pond 3/4 of a mile away. With one other helper and two long sticks, supposedly not one duck was lost.

We “quietly” write a fair amount of Management Liability coverage, including D&O and EPL, and recently a few of my customers have been asking what’s going on in the market. We represent a number of carriers, including Chartis, Travelers, Carolina Casualty and a couple of Lloyd’s facilities, in addition to USLI and Philadelphia.

I spoke to several companies to get their take, so the following is a composite of discussions with underwriters, claim staff and marketing reps. I’ll break this up into two posts to keep it short.

D&O Claims Are Up. There’s a slight increase, but not at the same level as Employment Practice Liability claims. More and more carriers are trying to sell management liability policies where D&O is included with EPL, Crime and Fiduciary coverage. That helps loss ratios and profitability where there are more premium dollars to pay EPL claims vs less frequent and/or less severe crime or D&O claims.

Community Associations – (Homeowner, Condo and Neighborhood Associations make us most of this class) Claim frequency has increased, but not to the extent where you’ll see any major adjustments from the insurance companies. The increase in frequency is in part driven by the economy. Lower real estate values can result in deficits in association funds, and resulting increases in assessments give way to disputes and legal action. Those same deficits also create opportunities for legal issues as repairs and maintenance and other related work may not be completed and resulting finger pointing invariably goes back to the board.

The Community Association product is still probably underpriced, but don’t expect to see more than a 5% or 10% increase in premiums unless the account has problems. More than likely underwriting eligibility and coverage rules have changed or will change to “make up” for carrier’s inability to get the rates they want.

Not For Profit – The situation here is almost exactly the same as for Community Associations in terms of rates, as there’s still a great deal of competition. Don’t expect much to change anytime soon.

Private Company – Claim frequency is increasing, and the common theme of claims being economically driven holds true here. Companies are in trouble financially and some are bankrupt. Extensive reviews of the books, trustees coming in to make their claims and other similar circumstances all contribute to the problem. There are also some claims resulting from M&A activity.

Rates are going up a little and that’s as much a result of EPL coverage claims as anything, since it's usually combined with the D&O. Also, coverage issues can be more complex these days so the cost to defend in those cases is almost always going to be higher.

Overall on D&O coverage noted above, there are very few new companies entering the market and if they do enter it’s usually in the form of management liability. Also, there’s not much new in the way of coverage expansion – the majority of additional coverage options have already been introduced to the market. And you can expect rates to be fairly similar to expiring unless there are issues with the risk.

EPL update will follow in the next post.

Monday, June 4, 2012

Coverage Update–New Option for Stand Alone Sexual Misconduct Liability

kcpq-tacoma-high-school-band-director-reigns-a-001Stadium High School, Tacoma WA, where the high school band director resigned after allegations of inappropriate sexual contact with a student. Photo from WGNTV.COM

The photo above is the one of the first I found simply because it’s a fairly recent event, but unfortunately I could have picked just about any state in the union for headlines about high school or college related sexual misconduct. And a similar sad story can be told concerning healthcare facilities, religious institutions and many, many others. The risk is real and profound, as recent headlines have all too often pointed out.

We’re now offering a new option for stand alone sexual misconduct coverage. This isn’t intended for a small risk, but really fills some possible coverage gaps for mid to large size entities, public and private. And it’s important to note this isn’t an afterthought with sub limits of $50,000 or $100,000. In this day and time a $50,000 limit just isn’t sufficient. Here’s a quick summary:

What Does the Policy Provide? Risk Management Advice and Broad Insurance Coverage for Liability and Costs of Defense Regarding Claims for Sexual Misconduct and Molestation and/or Negligent Hiring and Supervision.

Who’s Covered? Executive Directors, Trustees, Employees, Coaches, Counselors, Clergy and Volunteers.

What’s Included? Negligent Hiring, Employment, Investigation, Supervision, Training or Retention Of, Failure to Report Employees Who Commit Sexual Misconduct/Molestation.

Additional Benefits? Tailored Risk Management, Including Access to a Web Based Risk Management Tool. Employee and Volunteer Training Information. Early Loss Mitigation and Access to a Network of Expert Counsel.

Which Entities Are Targets? Religious Institutions, Educational Institutions, Leisure Services, Social Services and Healthcare Organizations.

Minimum Premium? $10,000 for $1 MILL Limit

Limits Available? Up to $5 MILL, Primary or Excess.

Call or email and ask for more information or an application.

Thursday, May 31, 2012

Agency E&O–Steps Toward Prevention

Ram and Steps Palm Springs CA

This is an artist’s creative rendering of a ram, with a landscape mural painted on its body, located outside at the Palm Springs (CA) International Airport. I can’t recall when this was taken – several years ago – so it’s possible “Mr. Ram” is gone now. I was actually looking for a photo with “steps” in it, and while the plants are in a “stepped” wall in the background, I just had to use the photo. I like it, and at the same time I can’t help but think “E&O”. You?


I just read an Insurance Journal blog post by a consultant (Chris Burand, Burand & Associates) and thought his comments/ideas are worth repeating. The basis of his post is that agents may be opening themselves up to E&O by not getting current underwriting information on renewals. The reasons for that are many, but could include:

  • No one asks the insured for updated info! This is perhaps even more likely when the policy is an “automatic” renewal, i.e. the carrier is really not asking for much in the way of info to be able to issue a renewal policy. That’s convenient but may not be the best way to protect your agency or your client.
  • The Insured isn’t all that interested in responding to another insurance information request (“…again? we just talked about this a few months ago…”), and the agency personnel that have the relationship to get the info aren’t involved, don’t want to take the time and effort, no one lets them know, etc.
  • The renewal info comes back and while it contains information that is in fact new or different, the renewal info is not compared to what’s in file from prior years.

The point is also made that if the agency is asking for updated information and discovers new or uncovered exposures, it may mean additional opportunities to provide coverage. That’s good for possible additional revenue production, as well as E&O prevention.

It would be nice if there was one simple form to use for every renewal, and of course there isn’t, but that isn’t a good reason not to make an attempt to develop renewal checklists that are meaningful. Your agency may already have done this, which is great, but it may have been several years ago. It could be time to take a hard look at those older forms.

Monday, May 14, 2012

Current Events: Sexual Abuse/Molestation

courtroomThe Children’s Bureau, a division of the US Department of Health and Human Services, reports that for the period from October 1, 2009 through September 30, 2010, there were 436,321 substantiated cases of child abuse and/or neglect. Of that number approximately 25% were categorized as physical or sexual abuse. That’s based on reported cases and does not contemplate incidents that were unreported. While any system attempting to codify child abuse is flawed for a variety of reasons, the number of abuse cases is staggering and has not gone unnoticed by law firms and others.

Recently one of the National Underwriter sites posted a column regarding the Penn State sexual abuse scandal and which insurance coverage(s) may or may not apply.  It appears the author is starting with the GL policy and will at some point address D&O and possibly EPL issues. http://www.propertycasualty360.com/2012/04/26/penn-state-vs-insurer-who-will-cover-sex-abuse-co

I have no idea what the insurance package for PSU includes, but I would certainly hope they have separate coverage or at least an additional coverage part that specifically addresses sexual abuse/molestation. I would expect to find that in an EPL policy written for the school. I’m guessing if they didn’t have that coverage in place previously they have it now, albeit at a greatly increased premium.

This particular scenario and the fact that it’s gained national attention is probably not something your client’s think can or will happen to them, but it doesn’t have to be a national scandal to ruin your customer’s business. All you need is a little local press concerning the alleged improper/illegal conduct of a private school, daycare center, assisted living facility or any of a hundred other possible entities who have responsibility for the safe keeping of others. Add to that the cost of defending the allegations and even if they’re exonerated they may not be able to recover their lost revenue.

In this day and age, it would seem that offering your client coverage for sexual abuse and molestation would automatically be on the checklist of things “to do”, even if it’s only a sub limit if that’s all you can find. For some classes and types of risks, I’ll admit it’s not an easy write and can be expensive, but if you don’t pursue it your client may end up paying costs out of pocket, and you may be filing an E&O claim. Neither situation is desirable.

Penn State will obviously live on, and it should, as the actions or lack thereof from a few people should not destroy an institution for all time. Your customers probably don’t have the staying power and resources of a major university, so at the very least they need a fighting chance to survive what could be a very damaging series of events.